Sell first or buy first?
How the order you move in changes your cash, your loans and where you sleep.
The short answer
There is no single right order. Selling first gives you certainty about your cash but may leave a gap with nowhere to live. Buying first gives you the home you want but means two loans for a while. The right choice depends on how much cash buffer you have and what kind of home you are buying.
Three ways to order it
Most HDB upgraders end up with one of these. Each trades one risk for another.
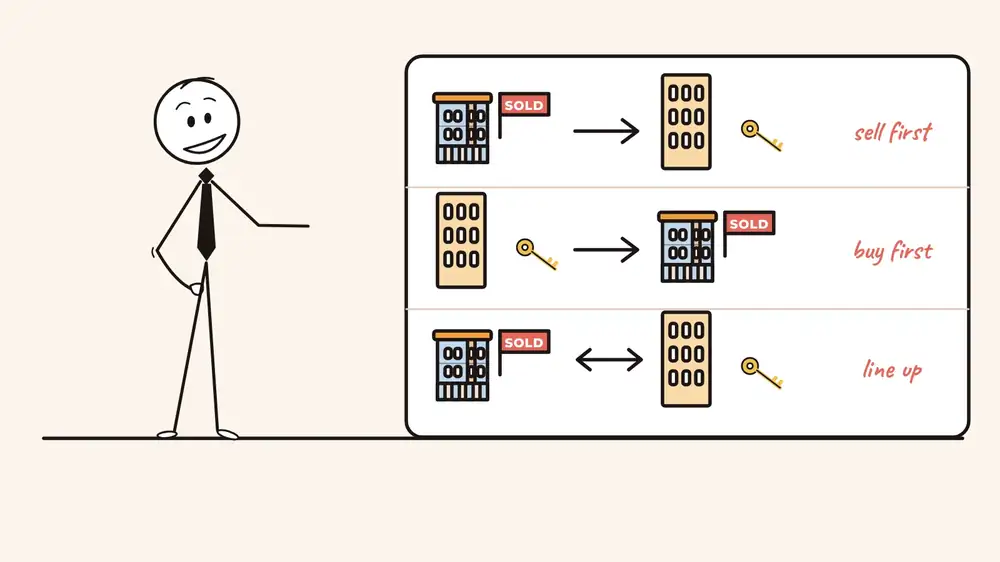
Sell first
You sell your flat, receive the proceeds, then buy and move into the new home.
- You want certainty about your cash, you have a place to stay in between, and you want to avoid paying ABSD upfront.
- A gap between homes. You may need to rent, store belongings and move twice.
Buy first
You commit to the new home first, then sell your flat within the time allowed.
- You have room to carry two loans for a short time, the cash to pay the ABSD upfront, and a good home is available now. Singles and non-married buyers need to budget for the ABSD as a cost.
- ABSD paid upfront, and a smaller bank loan while you still have a housing loan. Only married couples buying jointly can get the ABSD back, and only if they sell in time.
Line them up
You time the sale and the purchase to complete close together, so the gap is short.
- Your timelines are flexible and everyone involved can move on similar dates.
- It rarely lines up perfectly. Have a plan for a small gap, or a small overlap.
If you buy first: ABSD
When you already own a flat and buy a private home, the new one is your second residential property. That brings Additional Buyer’s Stamp Duty (ABSD), and it is payable upfront, when you buy. A married couple buying together, in both names, can get it back if they sell their flat in time. If you are buying alone, it generally cannot be refunded by selling your flat.
- Buying alone, or not married? The spouses’ remission does not apply, so the ABSD is not refunded by selling your flat. IRAS has a separate concession for some single Singapore citizens aged 55 and above, subject to conditions.
- Miss the date and the ABSD stays payable. Treat the deadline as fixed and plan your sale early.
- Plan cash for the full amount. Even though it can come back, you need it first.
- Selling first can avoid it. IRAS says that if you have already signed a contract to sell your only property before you accept the Option to Purchase for the new one, you do not need to pay ABSD.
- The bank lends less while you still have a loan. If you have an outstanding housing loan, the limit on a new bank loan can be as low as 45% of the price, and at least 25% of the price must be paid in cash. With no outstanding loan, the limit is usually 75%, with at least 5% in cash. This is why buying first needs so much more cash than selling first. The two couples in "Two couples, two routes" further down show the difference in numbers. (MAS)
- Thinking of an executive condo? ABSD works differently for a new EC. See Condo or EC.
Source: IRAS, Additional Buyer’s Stamp Duty (ABSD). Rates and conditions can change, and your situation may differ. Confirm with IRAS and your lawyer before you commit.
What it looks like over time
An illustration only. Real timelines depend on your sale, the new home and your bank.
Which route fits you?
Three quick questions. Tap an answer for each.
Try it
Tap one answer for each. You will see which route usually fits that situation.
A thinking aid, not advice. Nothing you tap is saved or sent.
The cost of a gap
If you sell first, or the dates do not match, the gap has a price. It is easy to miss in your first estimate.
Add storage, moving twice and any overlap in loan payments. The worksheet has a box for this, so it is counted in your cash left.
- Ask about staying on. Some buyers agree to let a seller stay a short time after completion. It has to be agreed and the rules apply, so check early.
- Know your deadline. If you are a married couple buying jointly and want the ABSD refunded, you must sell your flat within 6 months. Count from the purchase date, or from TOP or CSC if the home is still under construction.
- Keep a buffer for delays. Sales and loan approvals take time, and dates move.
Rules and rates change. Check current details with HDB, CPF Board, IRAS, MAS and your bank before you decide.
Two couples, two routes
The same $1,500,000 condo, bought in a different order. These are made-up examples to show the maths, not real clients.
Couple A: sells first
Married couple. HDB sells for $680,000, then they buy a $1,500,000 condo.
Couple B: buys first
Married couple, buying jointly. Completed $1,500,000 condo, flat not yet sold and still carrying a housing loan.
Why this matters. Buying first turns the question into one of cash on hand. The ABSD alone can be larger than your savings, even though it may come back later.
Illustrative numbers only. Agent fees are assumed at 2% of the sale price for illustration. Couple B assumes a bank loan limit of 45% because they still have a housing loan, so the minimum cash is 25% of the price (MAS). ABSD figures assume a Singapore citizen buying a second residential property, and the refund assumes a married couple buying jointly under the spouses’ remission rules. Confirm your own situation with IRAS and your lawyer.
A checklist before you commit
If you are leaning towards buying first, tick what is already true. Whatever is left is what to sort out before you sign.
Before you buy first
There is still a lot to sort out. Work out your numbers, then see whether selling first or lining them up fits better.
A thinking aid, not advice. Nothing you tap is saved or sent.
Three things to remember
Keep reading
More guides to read next
Related on this site
Next step
Plan your timing with real numbers
Put your expected sale, the new home and the gap into the worksheet. Then we can look at which order fits your cash and your timeline.
A real estate professional helping Singapore HDB owners work out their numbers before they upgrade to a condo or EC.
WhatsApp me